TRENDING
Sinking Funds Explained: A Smart Way to Save

10 min read
Last updated November 8, 2026
Some bills seem to come out of nowhere. The car needs new tires, the insurance renewal arrives or the holidays sneak up again.
But many of these costs are not true surprises. You know they are coming, even if you are not sure exactly when.
A sinking fund helps you prepare for these predictable expenses. This guide explains what sinking funds are, how they work and how to start your own.
Key Takeaways
- A sinking fund is money you save bit by bit for a known future expense.
- It is different from an emergency fund, which covers true surprises.
- Divide the total cost by the months until it is due to find your monthly savings goal.
- Automatic transfers make saving easier and more consistent.
- Sinking funds can help you avoid credit card debt for planned costs.
$100/moSaving $100 a month covers a $600 bill due in six months, an example from Thrivent.
What Is a Sinking Fund?
A sinking fund is savings you build gradually for a specific upcoming expense. When the bill arrives, the money is ready.
According to Thrivent, a financial services organization, you pay the expense once you reach your goal. Then you start a new fund if needed.
The idea is simple. Instead of facing one big bill, you break it into smaller monthly amounts.
Sinking Fund vs Emergency Fund
People often confuse these two types of savings. Both matter, but they serve different purposes.
| Feature | Sinking Fund | Emergency Fund |
|---|---|---|
| Purpose | Known, planned expenses | Unexpected costs |
| Timing | You know roughly when | Could happen anytime |
| Amount | You can estimate it | Often unknown |
| Examples | Holiday gifts, insurance, tires | Job loss, medical bills, sudden repairs |
| Goal | A set amount by a deadline | A cushion of several months |
The Consumer Financial Protection Bureau (CFPB) describes an emergency fund as cash set aside for unplanned costs. These include car or home repairs, medical bills or lost income.
Thrivent notes that sinking funds cover costs you can see coming. That means you can plan the amount and timeline ahead.
You need both kinds of savings. Sinking funds keep planned costs from draining your emergency cushion.
Which expense catches you off guard most often?
- Holidays
- Car repairs
- Insurance bills
- Not sure
Why Sinking Funds Help
Predictable costs can still wreck a budget if you are not ready. Many people end up putting them on a credit card.
The CFPB warns that without savings, even a minor expense can lead to credit card or loan debt. Some people even pull money from retirement accounts.
Sinking funds help in several ways.
- They spread big costs over many months.
- They reduce stress when bills arrive.
- They help you avoid high-interest debt.
- They protect your emergency fund for true emergencies.
- They give every dollar a clear job.
Common Sinking Fund Categories
Almost any planned expense can have its own sinking fund. Thrivent lists several common examples.
- Holiday gifts and celebrations
- Car insurance and health insurance premiums
- Property taxes
- Car maintenance, such as new tires
- Vacations and travel
- Home projects and repairs
- Charitable giving
Other popular categories include back-to-school costs, annual subscriptions, pet care and medical deductibles. Think about what caught you off guard last year.
Home maintenance is another big one. Furnace tune-ups, gutter cleaning and appliance repairs show up every year, even if the exact timing varies.
Our furnace maintenance guide explains how regular care can lower big repair costs. It can also help you avoid surprises.
Good to know. Your bank statements are a goldmine for spotting sinking fund categories. Look for bills that show up once or twice a year.
How to Start a Sinking Fund
Thrivent outlines a simple step-by-step process. You can set up your first fund in about 15 minutes.
Step 1. Pick an Expense
Choose one predictable cost to start. Holiday spending or car insurance are great first goals.
Look back at last year’s bank statements. Note large bills that arrived once or twice a year.
Step 2. Estimate the Total Cost
Use last year’s amount as a starting point. Add a little extra for price increases.
If you are not sure, round up. Having a bit more is better than coming up short.
Step 3. Set a Deadline
Write down when the money will be needed. For holidays, that might be early December.
For insurance, check your renewal date. Some premiums are due every six or twelve months.
Step 4. Do the Math
Divide the total cost by the number of months until the deadline. Thrivent gives a simple example.
If you need $600 in six months, save $100 a month. Use the calculator below to find your own number.
Sinking fund calculator
Already saved some? Subtract it from the total first.
Step 5. Choose Where to Keep It
Thrivent suggests a separate savings account or a savings bucket within an existing account. Many banks and credit unions let you create several named savings goals.
The CFPB says a bank or credit union account is generally one of the safest places for savings. Keeping funds separate makes it harder to spend them by accident.
Step 6. Automate Your Savings
Set up automatic transfers from checking to savings on payday. The CFPB recommends recurring transfers to build a steady savings habit.
Check your balance or set alerts so transfers do not cause overdrafts. Adjust the amount if your income changes.
Step 7. Spend It When the Time Comes
When the bill arrives, use the money in your sinking fund. That is exactly what it is for.
Then reset the fund for next time. Many sinking funds repeat every year.
- Pick one expense
- Estimate the total
- Set a deadline
- Divide by months
- Open a separate bucket
- Automate transfers
How Many Sinking Funds Should You Have?
Start small with one to three funds. Too many at once can feel overwhelming.
Focus on the expenses that cause the most stress. Add new funds as your budget allows.
Some people track a dozen categories, while others keep just a few. The right number is whatever you can manage consistently.
Fitting Sinking Funds Into Your Budget
Sinking funds work best as part of a full budget. Treat each monthly contribution like a regular bill.
If you follow the 50-30-20 budget rule, sinking funds often fit within the savings portion. Some planned costs, like insurance, may fit under needs.
Not enough room in your budget? Start with a smaller amount and increase it over time.
Quick tip. Give each savings bucket a clear name, like Holiday 2027. Seeing the goal makes you less likely to spend it.
Finding Money for Sinking Funds
Saving can feel hard when money is tight. These ideas can help you get started.
- Cancel unused subscriptions and redirect the savings.
- Save part of every raise or bonus.
- Put tax refunds or gift money toward your funds.
- Round up purchases and save the difference.
- Sell items you no longer use.
The Purdue University Extension suggests saving all or part of one-time money like tax refunds and holiday gifts. This works especially well for people with irregular income.
Our guide on how to cancel unused subscriptions can help you free up extra cash.
What is a sinking fund for?
- Unexpected emergencies only
- Known, planned expenses
- Daily spending
Sinking funds cover predictable costs, while emergency funds cover surprises.
Free updates
Join the Digieh list
Be the first to know when our weekly brief launches.
No spam. Unsubscribe anytime. Read our Privacy Policy.
Don’t Forget Your Emergency Fund
Sinking funds are not a replacement for emergency savings. You still need a cushion for true surprises.
Purdue Extension notes a common recommendation of three to six months of living expenses. That goal can take time, so start small.
The CFPB suggests estimating how much your most common unexpected expenses have cost in the past. Our guide on how to build an emergency fund explains more.
Some people build a small emergency fund first, then add sinking funds. Others work on both at the same time.
A Sample Sinking Fund Plan
Here is an example of how one household might plan its sinking funds.
| Fund | Yearly Cost | Monthly Savings |
|---|---|---|
| Holiday gifts | $900 | $75 |
| Car insurance | $1,200 | $100 |
| Car maintenance | $600 | $50 |
| Annual subscriptions | $240 | $20 |
| Vacation | $1,800 | $150 |
These numbers are only examples. Your amounts will depend on your own bills and goals.
Planning for holiday costs? Our holiday budget guide can help you set a realistic amount.
You need $1,200 in 12 months. How much should you save monthly?
- $100
- $50
- $200
Divide $1,200 by 12 months to get $100 a month.
Sinking Funds With Irregular Income
Freelancers, gig workers and commission earners face extra budgeting challenges. Sinking funds can make uneven income feel steadier.
The CFPB suggests tracking when money comes in and goes out. Save more during strong months to cover leaner ones.
Try setting a minimum monthly contribution you can always meet. Add extra whenever a bigger payment arrives.
Self-employed workers often keep a sinking fund for quarterly estimated taxes. Thrivent lists this as a common example.
Plan Your Funds for the New Year
Late fall is a great time to plan next year’s sinking funds. You can see this year’s costs clearly and set goals before January.
List every irregular bill you paid this year. Note the amount and the month it was due.
Then set up funds for the biggest ones. Starting in January gives you a full year to save for next holiday season.
Teaching Kids About Sinking Funds
Sinking funds are a great money lesson for children. The idea of saving a little at a time is easy to grasp.
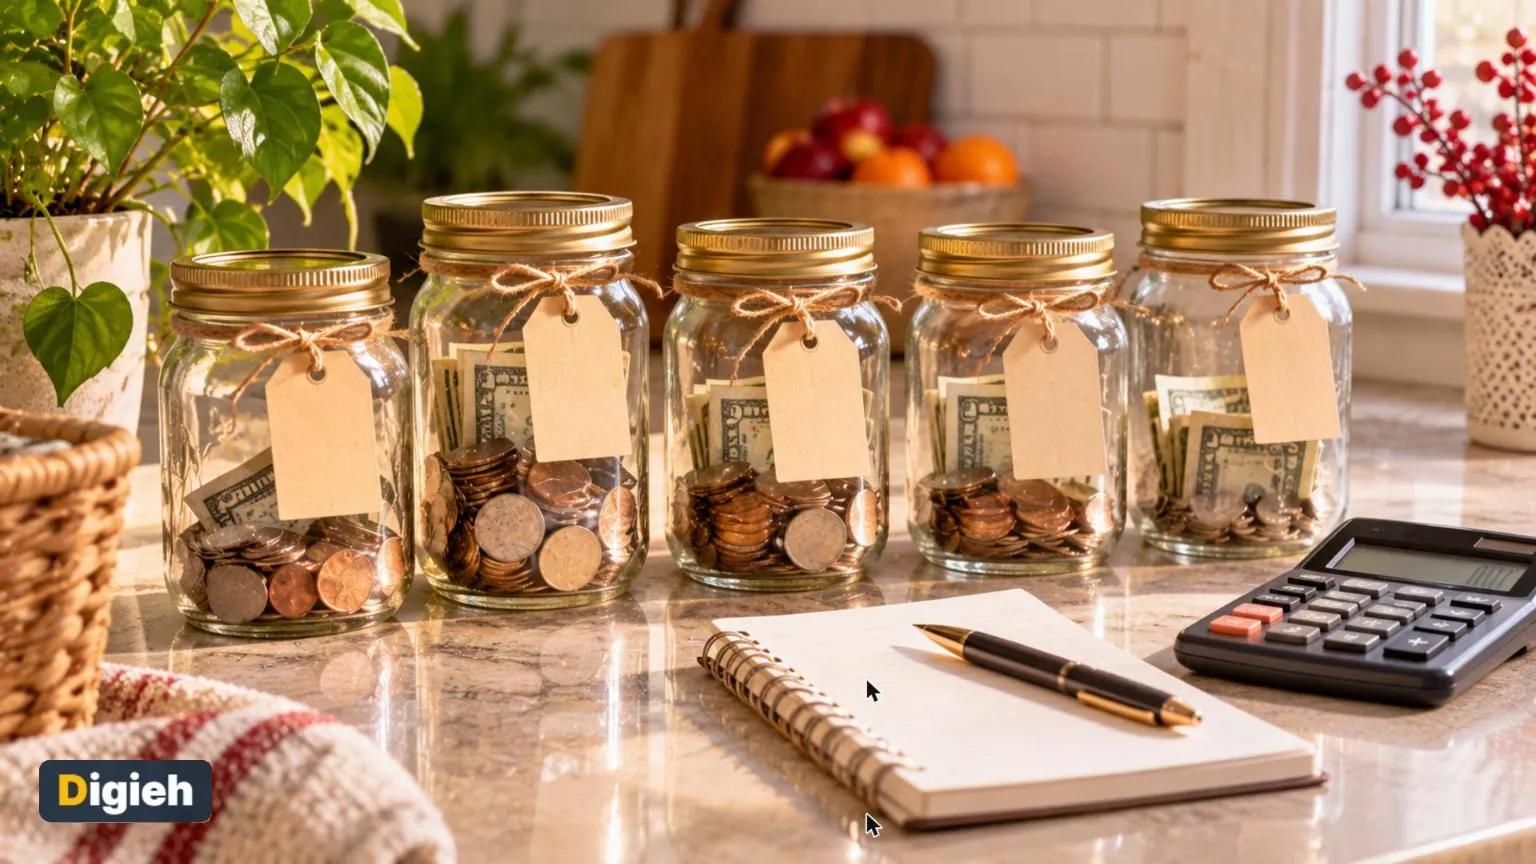
Give kids a few jars labeled for different goals, like a toy, a gift or a trip. Help them split allowance money among the jars.
Watching jars fill up teaches patience and planning. Those habits can last a lifetime.
Common Mistakes to Avoid
Sinking funds are simple, but a few mistakes can slow you down.
- Underestimating costs. Prices often rise, so add a buffer.
- Mixing funds with spending money. Keep savings separate.
- Skipping contributions. Consistency matters more than size.
- Borrowing from one fund for another. This can leave you short later.
- Starting too many funds. Begin with a few and grow over time.
If you do dip into a fund, make a plan to refill it. Life happens, and flexibility is okay.
Tracking Your Progress
Watching your balances grow is motivating. Choose a tracking method you will actually use.
- A simple spreadsheet with each fund in its own row
- Named savings buckets in your banking app
- A paper chart on the fridge
- Clear jars for cash savers
Review your funds once a month. Celebrate milestones, like reaching the halfway mark.
Sinking Funds and Debt Payoff
If you carry credit card debt, sinking funds can still help. They stop new debt from piling up when planned bills arrive.
Keep sinking fund contributions small while you pay down high-interest balances. Even a little saving prevents the next big bill from landing on a card.
Our guide on paying off holiday credit card debt shares strategies for tackling balances.
Try this today. Scan last year’s bank statements for three big once-a-year bills. Pick one and set up your first sinking fund.
Frequently Asked Questions
What is the difference between a sinking fund and savings?
A sinking fund is savings set aside for one specific, planned expense with a deadline.
How much should I put in a sinking fund?
Divide the total cost by the months until it is due. That is your monthly goal.
Where should I keep my sinking funds?
A separate savings account or named savings buckets work well. Keep them apart from spending money.
Should I build a sinking fund or emergency fund first?
Many people start with a small emergency fund, then add sinking funds for planned costs.
Can I have more than one sinking fund?
Yes. Many people keep several funds for different goals.
Conclusion
Sinking funds turn big, predictable bills into small, manageable steps. They reduce stress and help you avoid debt for costs you can see coming.
Pick one expense, divide the cost by the months you have and set up an automatic transfer. Small, steady savings add up faster than you think.
Found this useful?
Editor’s Note
This article is accurate as of November 8, 2026. It draws on guidance from the Consumer Financial Protection Bureau, Purdue University Extension and Thrivent. This is general information, not financial advice.
Spot an error in this article? Please contact us at support@digieh.com or read our Corrections Policy.
Keep exploring
Your next read is waiting
 1EntertainmentSecret Santa Rules and Gift Ideas Everyone Loves10 min read
 2HealthSinus Infection vs Cold: Simple Ways to Tell10 min read
 3SportsSnowshoeing for Beginners: Easy Guide to Winter Trails10 min read
 4Food & LifestyleEasy Pot Roast Recipe That Turns Out Tender10 min read
 5TechnologyHow to Choose the Best Home Wi-Fi Router10 min read
 6BusinessHow to Avoid Burnout at Work: Proven Tips10 min read