TRENDING
Home Insurance Claim Steps That Protect Your Payout

7 min read
Last updated November 17, 2026
To file a home insurance claim, call your insurer quickly, photograph all damage and make only temporary repairs. Then keep every receipt and meet the adjuster in person.
Those first steps protect your payout more than anything else. This guide walks you through the whole process, from the first call to the final check.
Key Takeaways
- Report the damage to your insurer as soon as you can.
- Take photos and videos before you clean up or repair anything.
- Make only temporary repairs until the adjuster has seen the damage.
- Keep receipts for repairs, hotel stays and replaced items.
- Never pay a contractor in full up front or in cash.
Jump to a section
- Decide whether to file
- Step-by-step claim process
- Working with the adjuster
- How claim payments work
- Avoiding contractor scams
- Build a home inventory
- If you disagree with the offer
Decide Whether to File
Start by finding your deductible on your policy. That is the amount you pay before the insurer pays anything.
The National Association of Insurance Commissioners (NAIC) suggests a simple test. File when repairs will clearly cost more than your deductible or the damage is widespread.
Small damage just above the deductible may not be worth a claim. You would get little money back for the effort.
| Situation | Usually worth a claim | Why |
|---|---|---|
| Repairs cost far more than your deductible | Yes | The payout is meaningful |
| Major storm, fire or water damage | Yes | Costs often grow once repairs start |
| You cannot live in the home | Yes | Your policy may pay extra living costs |
| Repairs cost less than your deductible | No | The insurer would pay nothing |
| Minor wear, such as an old leaking tap | Usually no | Policies rarely cover normal wear |
Good to know. Unsure how big the damage is? Report it anyway and ask questions. Reporting deadlines vary by state, so waiting can hurt.
Step-by-Step Claim Process
Follow these steps in order. Each one builds the proof your insurer needs to pay you fairly.
1. Make sure everyone is safe
Leave the home if it is unsafe. Turn off water or power only if you can do so safely.
2. Call your insurer or agent
Report the damage as soon as you can. Have your policy number, name, address and phone number ready.
The Texas insurance department notes that some policies set a one-year filing deadline. Other states and policies differ, so check yours.
3. Photograph and film the damage
Take wide shots of each room, then close-ups of every damaged item. Do this before you clean up or throw anything away.
Film a slow walk through the home while describing what you see. Date stamps on phone photos help prove timing.
4. Make temporary repairs only
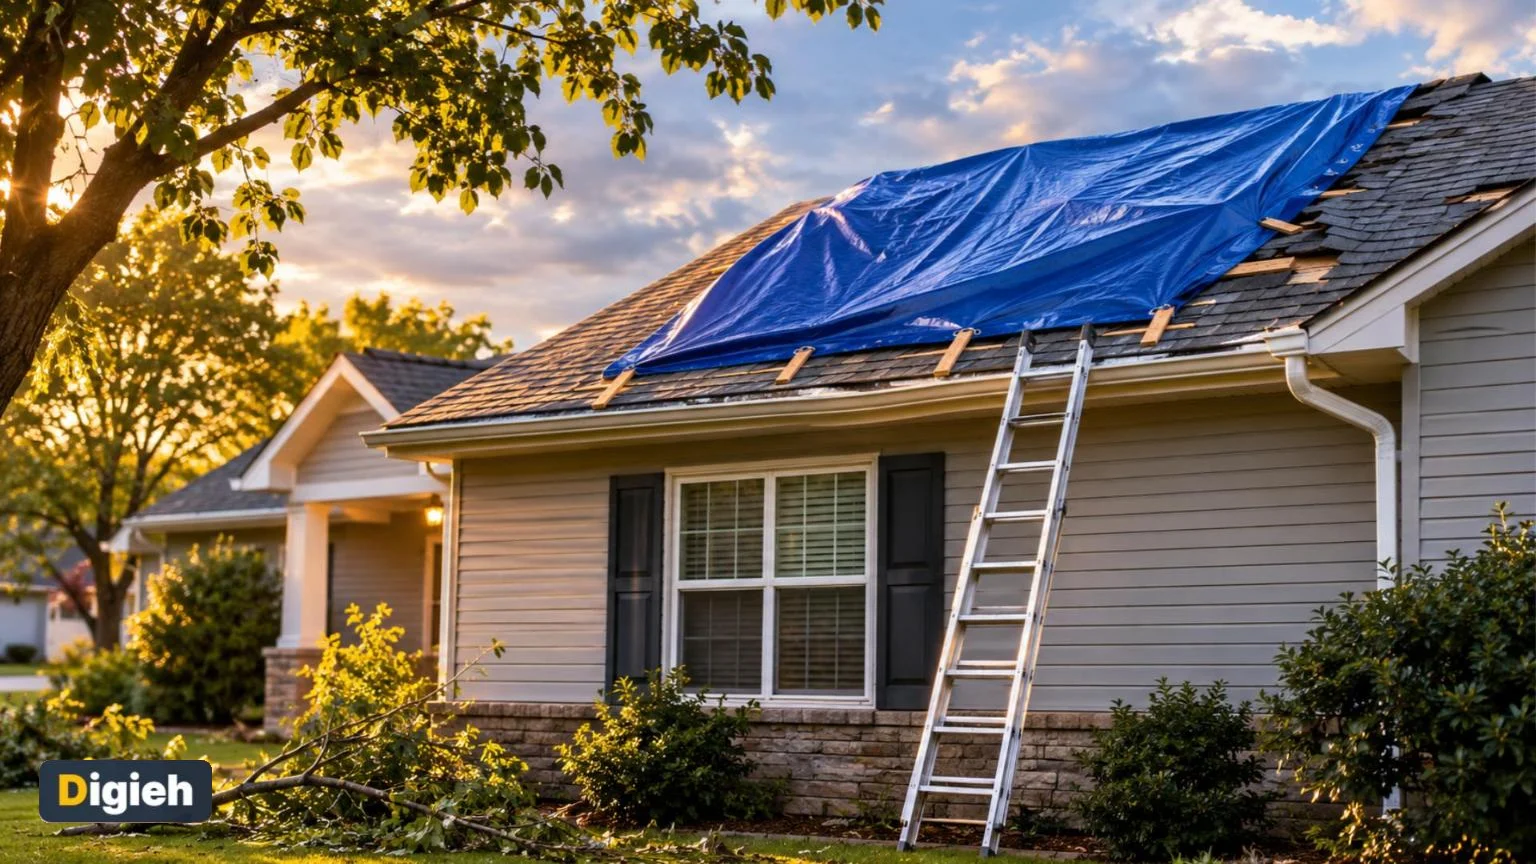
Stop further damage with simple fixes, such as tarping a roof or boarding a window. Texas regulators warn that permanent repairs too early could lead to a denial.
Keep damaged items if you can, so the adjuster can see them.
5. List every damaged item
Write down each item, its rough age and what it would cost to replace. Online store prices help you estimate.
6. Keep every receipt
Save receipts for tarps, repair supplies, hotel stays and new items. The NAIC says these receipts serve as proof for your claim.
Quick tip. Make one folder, on paper or on your phone, for the claim. Put every photo, receipt, email and note in it.
Have you ever filed a home insurance claim?
- Yes, it went smoothly
- Yes, it was a struggle
- Never
- Not sure
Working With the Adjuster
The insurer sends an adjuster to inspect the damage and estimate repair costs. Their report shapes your payout.
- Be home for the visit, and show every damaged area.
- Hand over your damaged property list and photos.
- Ask for a copy of the adjuster’s estimate.
- Invite your contractor to the visit if you have one.
- Write down the adjuster’s name and claim number.
The NAIC suggests having your contractor meet you and the adjuster. That way, you can discuss both repair estimates together.
How fast insurers must act
Deadlines depend on your state. Texas, for example, sets clear timelines for insurers.
| Stage | Texas deadline |
|---|---|
| Acknowledge your claim | Within 15 days |
| Accept or deny after getting all information | Within 15 business days |
| Pay after agreeing to pay | Within 5 business days |
These timelines come from the Texas Department of Insurance. Check your own state insurance department for local rules.
How Claim Payments Work
Payments can arrive in parts, and the check may name more than one person. Knowing this avoids surprises.
If you have a mortgage
The check is usually made out to you and your lender. The lender often releases the money in stages as repairs finish.
Replacement cost policies
Many insurers pay in two steps. The first payment subtracts depreciation and your deductible.
Texas regulators explain that the insurer pays the withheld depreciation after repairs. Keep your repair receipts to claim it.
Extra living expenses
If you cannot live at home, your policy may pay for a hotel, meals and other extra costs. Insurers call this additional living expenses.
There is a dollar limit, often 10 to 20 percent of your dwelling coverage, says the Texas guide. Track spending so the money lasts until repairs finish.
Renting instead of owning? Our guide to renters insurance explains what tenants can claim.
Free updates
Join the Digieh list
Be the first to know when our weekly brief launches.
No spam. Unsubscribe anytime. Read our Privacy Policy.
Avoiding Contractor Scams
Scammers often arrive right after storms and disasters. The US Federal Trade Commission shares clear warning signs.
- Check the contractor’s license with your state or county.
- Ask for proof of insurance before work starts.
- Get several written estimates, not just the cheapest one.
- Sign a written contract with dates and a payment plan.
- Pay by credit card or check, never cash, gift card or wire.
The FTC also warns against signing over your insurance check to a contractor. Ask your bank to pay them in stages instead.
Report suspected fraud at ReportFraud.ftc.gov.
15 daysTime a Texas insurer has to acknowledge your home claim, says the Texas Department of Insurance.
Build a Home Inventory Before You Need It
A claim is much easier when you already know what you own. The NAIC urges people to record the contents of every room before disaster strikes.
- Photograph or film each room, including closets and drawers.
- Give extra attention to valuables such as jewelry, electronics and collectibles.
- Note brand names, models and rough purchase dates where you can.
- Store a copy away from home, such as in secure cloud storage.
- Update the list once a year and after big purchases.
The NAIC also offers a free Home Inventory App to help with this task. A simple phone video works well too.
If you have no records after a loss, do not panic. Old photos from family and friends can fill gaps, and online stores show current prices.
If You Disagree With the Offer
First, ask the insurer to explain the offer in writing. Then compare it with your contractor’s estimate line by line.
- Send extra photos, receipts or estimates that support a higher amount.
- Ask whether your policy offers appraisal for amount disputes.
- Consider a licensed public adjuster, who works for you for a fee.
- File a complaint with your state insurance department.
Appraisal settles disagreements about the amount, not about what the policy covers. Texas regulators note that the umpire’s decision is binding.
- Report the damage to your insurer
- Photograph and film every damaged area
- Make temporary repairs only
- Save all receipts in one folder
- Get written estimates from licensed contractors
Prevention helps too. See our guides on frozen pipes and power outage preparedness.
This article is for information only and is not legal or financial advice. Your policy wording decides what your insurer covers.
Try this today. Walk through your home with your phone camera running. Film every room and open each closet. This home inventory makes any future claim faster.
Test Yourself
What should you do before cleaning up storm damage?
- Photograph and film it
- Throw out broken items
- Start permanent repairs
Photos and video taken first are your best proof of the damage.
Which payment method is safest for a repair contractor?
- Cash
- A gift card
- A credit card
The FTC advises paying by credit card or check, never cash, gift cards or wire transfers.
Frequently Asked Questions
Will filing a claim raise my premium?
It can. Ask your insurer or agent how a claim may affect your renewal price.
Can I choose my own contractor?
Usually, yes. Get written estimates and share them with your adjuster.
What if I have no photos of my belongings?
Check old phone photos and pictures from family. Online store prices can help you estimate values.
How long does a home insurance claim take?
It depends on the damage and your state rules. Simple claims can settle in weeks, while large ones take longer.
Conclusion
A strong home insurance claim starts in the first hours. Report quickly, document everything and make only temporary repairs.
Your next step is to film a quick home inventory today, before you ever need it.
Keep your claim folder safe until the final payment arrives.
Found this useful?
Editor’s Note
This guide is accurate as of November 17, 2026. It draws on the NAIC, the Texas Department of Insurance and the US Federal Trade Commission.
Claim rules and deadlines vary by state and policy. Check your own policy and your state insurance department for details.
Spot an error in this article? Please contact us at support@digieh.com or read our Corrections Policy.
Keep exploring
Your next read is waiting
 1NewsWhat Really Causes a Nationwide Blackout, Explained Simply6 min read
 2Fitness & ExerciseHow to Exercise Safely Outside in Cold Weather8 min read
 3Education & CareersHow to Make a Study Timetable That Works7 min read
 4InsuranceHealth Insurance Terms Explained Simply With Real Examples8 min read
 5Parenting & FamilyHealthy Lunchbox Ideas Your Kids Will Actually Eat7 min read
 6PhonesShould You Buy a Refurbished Phone? Smart Checks8 min read