TRENDING
Lease vs Buy a Car? Smart Money Guide

8 min read
Last updated November 17, 2026
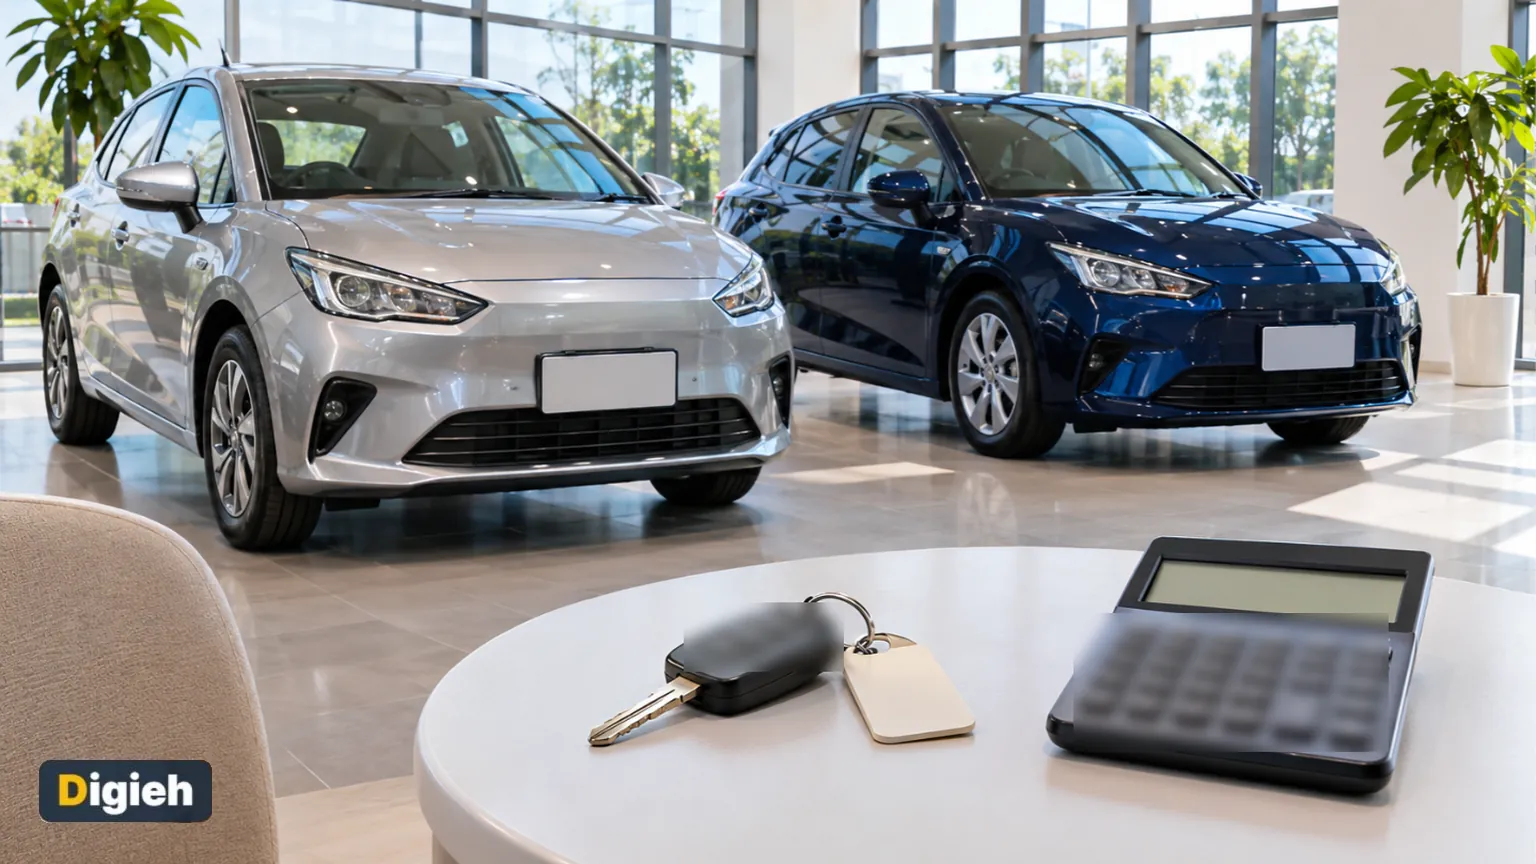
Buying a car usually costs less in the long run, because you keep the car after the loan ends. Leasing often gives lower monthly payments, but you own nothing at the end.
So the right choice depends on how long you keep cars and how much you drive. This guide compares lease vs buy a car with official consumer advice and a calculator for your own numbers.
For information only. This guide is not financial advice. Prices, rates and deals change often and vary by dealer and state.
Key Takeaways
- Lease payments cover the car's loss in value plus a rent charge, taxes and fees.
- Most leases limit you to 15,000 miles a year or less.
- Loan payments may be higher, but each one builds ownership.
- Ending a lease early can bring a large termination charge.
- Compare the total cost over the same period, not just the monthly payment.
In this guide
- How each option works
- Side-by-side comparison
- Who each option suits
- Compare your real costs
- Lease words to know
- Hidden lease costs
- Tips to get a better deal
- Frequently asked questions
How Does Leasing Work Compared With Buying?
When you lease, you pay to use a car for a set time and a set number of miles. At the end, you hand it back unless your contract lets you buy it.
When you buy with a loan, each payment lowers what you owe. Once the loan is paid, the car is yours to keep, sell or trade.
The Federal Trade Commission explains that lease payments are usually lower for the same car. That is because you only pay for the value the car loses during your lease.
What your lease payment pays for
Each monthly lease payment covers three parts. These are the expected drop in the car's value, a rent charge to the lender, and taxes and fees.
The consumer bureau gives a simple example. A $20,000 car expected to be worth $8,000 later loses $12,000 in value. Over 36 months, that is about $333 a month before the rent charge and taxes.
Lease vs Buy a Car Side by Side
We placed the advice from two government consumer agencies next to each other. Here is how leasing and buying compare on the points that matter.
| What matters | Leasing | Buying |
|---|---|---|
| Who owns the car | The leasing company | You, once the loan is paid |
| Monthly payment | Often lower | Often higher |
| Miles you can drive | Usually 10,000 to 15,000 a year | No limit |
| Wear and damage | Fees for extra wear at the end | Lowers resale value only |
| Typical length | 2 to 4 years | 3 to 7 years |
| Ending early | Termination charges may apply | Sell the car anytime |
| At the end | Return it or buy it if allowed | Keep it with no payments |
Sources are the consumer bureau guide to leasing versus buying and the trade commission guide to leasing.
15,000Yearly mileage limit or less in most standard leases, according to the Federal Trade Commission.
Who Each Option Suits
Leasing suits
People who like a new car every few years and drive fewer miles. It also suits drivers who want lower monthly payments and the newest safety features.
Buying suits
People who keep cars for many years and drive a lot. After the loan ends, you enjoy years with no car payment at all.
Buying also suits anyone who wants to modify a car or carry pets and gear without worrying about wear fees.
- I want a new car every two to four years
- I keep my cars for many years
- I drive more than 15,000 miles a year
- I want the lowest monthly payment
- I want to own something at the end
- I have kids or pets that are hard on cars
- I want the newest safety features often
Compare Your Real Costs
Monthly payments can fool you. The fair test is what you pay over the same number of months, minus what the car is still worth.
Enter real quotes from a dealer below. Use the same car and the same time period for both options.
Total lease cost
Real cost of buying
Use the same number of months in both boxes. The lower result is the cheaper choice for that period.
The sample numbers are only placeholders, not real prices. Replace every box with your own quotes for a fair answer.
Ask your lender for the payoff amount, which is the loan balance still owed after those months.
Quick tip. Ask every dealer for a written out-the-door price. It shows taxes and fees, so you can compare quotes fairly.
Lease Words You Should Know
Lease contracts use their own terms. Knowing them helps you spot a bad deal.
- Residual value. The car's expected worth when the lease ends. It also sets your buyout price if the contract allows a purchase.
- Rent charge. A monthly fee the lender charges for letting you use the car. Some dealers call it the money factor.
- Mileage allowance. The miles you can drive each year without extra charges.
- Purchase option. A clause that lets you buy the car at the end of the lease.
The consumer bureau's leasing guide suggests asking how the residual value was set. A wrong estimate changes both your payment and your buyout price.
Free updates
Join the Digieh list
Be the first to know when our weekly brief launches.
No spam. Unsubscribe anytime. Read our Privacy Policy.
Hidden Lease Costs to Watch
Leases can look cheap until the final bill arrives. Watch for these charges before you sign.
- Extra mileage fees when you go over the yearly limit.
- Charges for wear, damage or missing equipment when you return the car.
- A large early termination charge if you end the lease early.
- End-of-lease fees for returning the car.
- Optional add-ons, such as service plans, that raise the price.
The Federal Trade Commission also notes that you must follow the maker's service schedule. You must carry insurance that meets the leasing company's rules too.
Higher insurance can change the math. Our guide on how to lower car insurance can help either way.
Which will you choose for your next car?
- Lease
- Buy with a loan
- Pay cash
- Not sure
Tips to Get a Better Deal
Both choices leave room to negotiate. The consumer bureau lists several parts of the deal you can bargain on.
- Negotiate the price of the car first, before you talk about payments.
- Ask about the down payment and whether a smaller one makes sense.
- Compare the rent charge or loan interest rate with other lenders.
- Pick a mileage limit that matches how much you really drive.
- Read every add-on and say no to the ones you do not need.
Loan interest works much like card interest. Our guide to how credit card interest works explains the basics.
Thinking about an electric car?
Battery technology changes fast. If you worry a new model may feel dated soon, a shorter lease is one option to weigh. Compare options in our electric vehicle vs hybrid guide.
Your Lease or Buy Checklist
- Count how many miles you drove last year
- Decide how long you usually keep a car
- Get written quotes for both a lease and a loan
- Compare total cost over the same months
- Read the mileage, wear and early ending rules
- Say no to add-ons you do not need
Try this today. Check your car's odometer and divide the miles by its age in years. That gives your real yearly mileage.
If a dealer pushes hidden charges or false promises, report it at ReportFraud.ftc.gov.
Test Yourself
What do most lease payments mainly pay for?
- Full ownership of the car
- Only the insurance
- The value the car loses during the lease
Lease payments cover the expected drop in value, plus a rent charge, taxes and fees.
Who usually does better buying instead of leasing?
- A driver who keeps cars for many years
- A driver who wants a new car every two years
- A driver who drives very few miles
Buyers who keep a car long enjoy years with no payments.
Frequently Asked Questions
Is it cheaper to lease or buy a car?
Buying usually costs less over many years because you keep the car. Leasing can cost less each month in the short run.
What happens if I drive over my lease miles?
You will likely pay an extra fee for each mile over the limit when you return the car.
Can I end a car lease early?
Usually yes, but you may pay a large early termination charge. You cannot just return the car and stop paying.
Can I buy my car at the end of a lease?
Yes, if your contract has a purchase option. The price is usually the residual value set at the start.
Conclusion
Lease if you want lower payments, drive fewer miles and like changing cars often. Buy if you keep cars for years and want to own something at the end.
Your next step is to get two written quotes and run them through the calculator. Then plan upkeep with our car maintenance checklist.
Found this useful?
Editor’s Note
This guide is accurate as of November 17, 2026. It draws on consumer guides from the Consumer Financial Protection Bureau and the Federal Trade Commission.
Prices, rates and lease deals change often. Always read your own contract before you sign.
Spot an error in this article? Please contact us at support@digieh.com or read our Corrections Policy.
Keep exploring
Your next read is waiting
 1RecipesEasy Shakshuka Recipe With Eggs in Tomato Sauce7 min read
 2Fitness & ExerciseHow Much Exercise Per Week? A Simple Guide7 min read
 3Parenting & FamilyHealthy Lunchbox Ideas Your Kids Will Actually Eat7 min read
 4TechnologyHow to Convert a PDF to Markdown for Notes and AI4 min read
 5Education & CareersHow to Take Notes With the Cornell Method7 min read
 6InsuranceTerm vs Whole Life Insurance, Which Is Better?7 min read